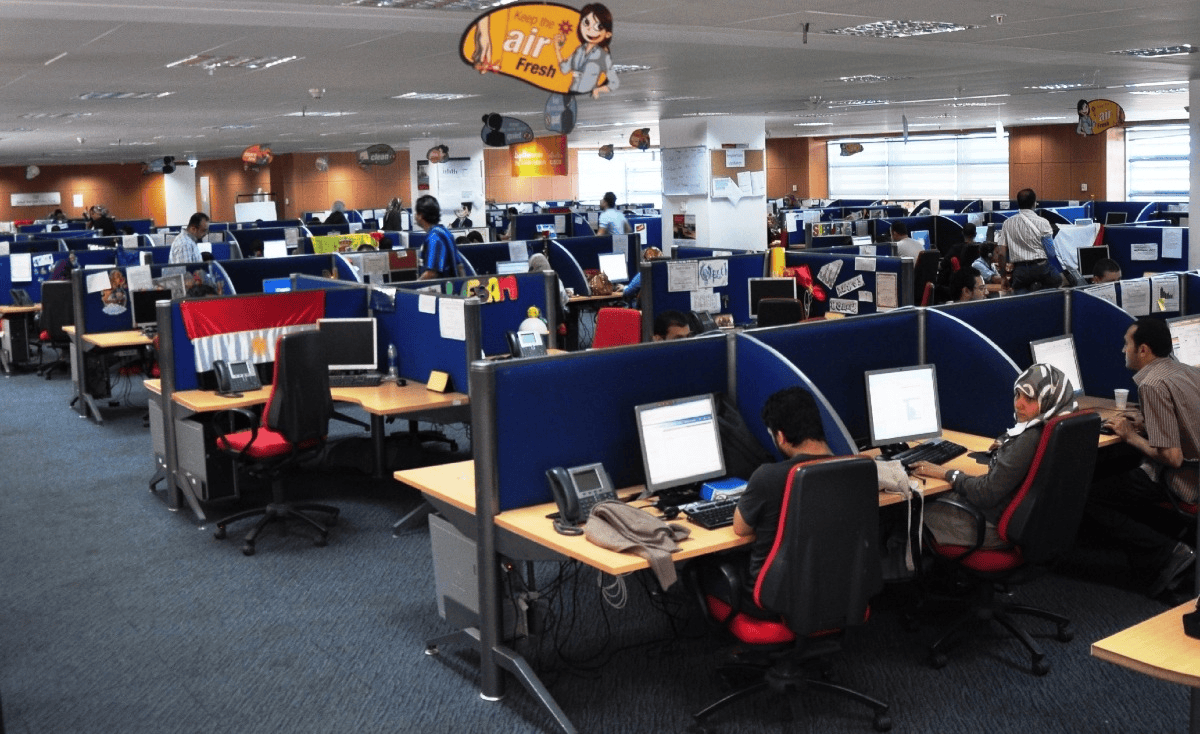
A telephone survey in Egypt market is no longer a "nice to have" research exercise; it is a strategic necessity for international businesses trying to navigate an economy where inflation, instalment finance and private-sector sentiment are changing faster than most reports can capture with
urban inflation at 14.9% in July 2026, consumer financing surging by 88.5% in the first half of 2026, and the non-oil private sector moving back toward stabilisation in August 2026, assumptions from six months ago are already outdated.
This article lays out what is really happening with consumers, businesses and the broader economy and why a well-designed telephone survey in Egypt market is one of the most effective ways for international companies to see opportunities and risks clearly.
The Economy: Growth, Inflation and Pressure Points
Egypt's economy in September 2026 presents a complex picture. Real GDP growth held around 5% in early 2026, supported by non-oil activity, manufacturing and a partial recovery in Suez Canal revenues. At the same time, headline inflation accelerated to 14.9% year-on-year in July 2026, up from 14.3% in June, interrupting a prior easing trend.
For businesses, this combination means:
- Demand is still present, but consumers are more selective and price-sensitive.
- Companies face higher input costs and must decide how much to pass on to customers.
- Categories linked to essentials, value and flexible payment terms are outperforming.
The trade data reinforces this tension. CAPMAS reported that Egypt's trade deficit widened by 58.5% year-on-year in June 2026 to $7.5 billion, even as total monthly exports jumped 37.4% to $5 billion, led by petroleum products and garments. In other words, external demand is improving, but domestic buyers are still grappling with high import bills and currency pressures.
A telephone survey in Egypt market helps international firms understand how these macro trends translate into everyday decisions: which products consumers are cutting back on, where they are switching brands, and how they are financing purchases.
Consumers: Instalments, Inclusion and Changing Behaviour
Instalments are now central to consumption
Consumer finance is no longer a niche segment in Egypt; it is a mainstream way of buying. The Financial Regulatory Authority (FRA) reported that consumer financing leapt 88.5% in H1 2026 to EGP 71.839 billion, with beneficiaries rising 75.7% year-on-year. Other FRA data shows regulated consumer-finance disbursements reached around EGP 96.27 billion in 2025, up 57%, with electronics and appliances accounting for 25.5% of financing, vehicles 15.9% and mobile phones the fastest-growing category.
Average instalment purchases run around EGP 6,900 as of January 2026, indicating that mid-ticket items—phones, appliances, furniture, even some vehicles are increasingly financed rather than paid in cash. For international brands, this has several implications:
- Pricing conversations must include monthly payment affordability, not just total price.
- Partnerships with finance providers can be as important as distribution partnerships.
- Communication should highlight approval speed, documentation requirements and transparency around fees.
A telephone survey in Egypt market can measure who uses instalments, for what categories, through which providers, and what concerns remain around consent, data privacy and over-indebtedness (Egypt consumer finance boom faces trust test, FRA issues Egypt's 1st comprehensive consumer finance guidebook).
Financial inclusion is rising, but trust is being tested
By the end of June 2026, 79% of Egyptians aged 15 and above about 56.4 million people held active transaction accounts, up from 77.6% at the end of 2025. Mobile wallets, bank accounts and prepaid cards are becoming everyday tools for paying, borrowing and saving.
At the same time, rapid growth has raised concerns, Reports highlight cases where loans were registered without explicit customer consent, prompting warnings that expansion could undermine confidence unless verification and disclosure improve. The FRA has responded by issuing Egypt's first comprehensive consumer-finance guidebook, detailing rules and regulations for the sector.
For lenders, fintechs and merchants, a telephone survey in Egypt market can:
- Measure awareness and usage of different finance providers.
- Identify trust drivers and red flags in the customer journey.
- Test messages around consent, transparency and data protection.
- Segment customers by risk tolerance, digital comfort and repayment experience.
Coping strategies are reshaping demand
Households are adapting to higher prices in multiple ways: buying smaller pack sizes, switching to local or lower-priced brands, delaying non-essential purchases, and relying more heavily on instalments and structured consumer financing. The cabinet has also announced plans to widen the scope of its new cash-subsidy framework to include a broader basket of essential food staples beyond traditional ration-card items.
These coping strategies mean that:
- Historical sales data may no longer predict future behaviour accurately.
- Brand loyalty is being tested by affordability and availability.
- Promotions, bundle offers and flexible payment options carry more weight.
A telephone survey in Egypt market captures these dynamics in real time, allowing companies to adjust pricing, packaging and communication before market share erodes.
Businesses: Private-Sector Sentiment, Hiring and New Companies
PMI signals stabilisation after months of contraction
The S&P Global Egypt PMI provides a monthly snapshot of conditions in the non-oil private sector. After seven consecutive months of contraction in 2026, the headline PMI rose to 49.6 in August 2026, up from 46.8 in July, marking the softest deterioration in operating conditions since January 2026.
Key takeaways from the August PMI:
- New orders and output continued to fall, but at much slower rates than before.
- Employment increased for the first time since October 2025, with job creation reaching the second-fastest pace in the survey's more than 15-year history.
- Business confidence climbed to its highest level in over four years, even though the index remained just below the 50 threshold that separates growth from contraction.
For international businesses, this suggests that:
- The worst of the demand contraction may be easing, but caution remains.
- Companies are starting to hire again, albeit cautiously, as backlogs stabilise.
- Sentiment is improving, even if actual order books are still weak.
A telephone survey in Egypt market targeting B2B decision-makers can complement PMI data by exploring:
- Which sectors are seeing the strongest recovery in orders.
- How companies are managing input costs and supply delays.
- Whether firms are investing in new products, markets or digital tools.
- What barriers are preventing them from expanding despite improved confidence.
Record company creation alongside weak orders
Another striking trend is the pace of new business formation. Egypt saw the establishment of approximately 26,500 companies in the first half of 2026, up nearly 20% from H1 2025. This indicates that entrepreneurs and investors still see opportunity, even as existing firms report weak new orders and ongoing price pressures.
This divergence creates both opportunity and risk:
- New companies represent potential customers for B2B services, from banking and insurance to software and logistics.
- High failure rates are possible if demand does not pick up quickly enough.
- Competitive intensity may increase in certain sectors as new entrants fight for limited orders.
A telephone survey in Egypt market can help international B2B providers identify which types of new companies are most active, what services they need, and how they prefer to be approached.
Unemployment and labour-market signals
Egypt's unemployment rate fell to 5.8% in Q2 2026, while employment rose 0.8% to 33.6 million, according to recent data. The PMI also reported near-record hiring in August 2026, particularly in roles linked to accumulated work backlogs.
For consumer-facing businesses, this suggests:
- More households have some form of earned income, even if real wages are under pressure.
- Employment growth may support baseline consumption in essential categories.
- However, job quality, wage levels and contract types still shape purchasing power.
Telephone research can probe how different employment groups—public sector, private formal, informal, gig workers—perceive their financial situation and adjust spending.
Why Telephone Research Specifically, Not Just Any Research
In this environment, many international teams ask: "Why not just use online surveys, desk research or third-party reports?" The answer lies in coverage, speed and depth.
Coverage that matches the real market
Online-only surveys in Egypt risk over-representing young, urban, digitally connected consumers while under-representing older age groups, lower-income households and rural populations. Yet these groups are often central to volume sales in categories like food, household goods, basic durables and entry-level financial services.
A telephone survey in Egypt market can:
- Reach respondents across governorates without requiring travel to each location.
- Include both mobile and landline users to reduce coverage bias.
- Apply quotas for region, urban/rural location, age, gender and income.
- Screen for relevant behaviours such as recent purchases, finance usage and business role.
This ensures that insights reflect the actual market, not just the most visible segment.
Speed when conditions are changing fast
Desk research and syndicated reports are valuable for context, but they often lag by months. In an economy where inflation, finance usage and business sentiment can shift within a quarter, waiting for the next published report can mean making decisions on stale data.
A well-managed telephone survey in Egypt market can:
- Field a study within days of questionnaire finalisation.
- Deliver initial results within one to two weeks for many projects.
- Be repeated periodically to track changes in sentiment, affordability and behaviour.
For international teams planning launches, pricing changes or market-entry timing, this speed is critical.
Depth through conversation, not just clicks
Telephone interviews allow trained Arabic-speaking interviewers to:
- Clarify questions when respondents seem unsure.
- Probe beyond "yes/no" answers to understand reasons and concerns.
- Explore sensitive topics like income, debt and trust with appropriate language.
- Capture nuanced feedback on brands, providers and policies.
This conversational depth is difficult to achieve with self-completed online forms, especially when respondents are time-pressed or wary of sharing financial information.
What International Businesses Should Be Asking Right Now
Based on current trends, here are priority questions a telephone survey in Egypt market can help answer.
For consumer brands and retailers
- How are rising prices affecting purchase frequency, pack-size choices and brand switching in your category?
- Which consumer groups are turning to instalments and BNPL, and which providers do they trust?
- Where do consumers discover new products, and what role do promotions, recommendations and social media play?
- How do attitudes differ between Cairo, Alexandria, Delta towns and Upper Egypt?
- What would make consumers willing to try a new brand or pay a premium?
For banks, fintechs and consumer-finance providers
- Which segments are most aware of and active in consumer finance, mobile wallets and digital banking?
- What are the main trust barriers: fees, consent, data privacy, collection practices?
- How do customers compare providers: speed, documentation, limits, customer service?
- Where are complaints or negative experiences concentrated?
- What messages around transparency and protection resonate most?
For B2B and industrial companies
- Which sectors are seeing the strongest recovery in orders and backlogs?
- How are companies managing input costs, supply delays and currency risk?
- Are firms investing in new equipment, digital tools or market expansion?
- What factors influence supplier selection: price, credit terms, delivery reliability, after-sales support?
- How do new companies differ from established firms in needs and decision processes?
For investors and market-entry teams
- Which governorates and demographics show the strongest combination of income, employment and spending?
- Where is informal activity still dominant, and how does that affect distribution and data?
- What regulatory or operational concerns are top of mind for local partners?
- How do local stakeholders perceive political and economic stability over the next 12–24 months?
A telephone survey in Egypt market can be tailored to each of these audiences, with custom sampling and questionnaires aligned to specific decisions.
Designing a Telephone Survey in Egypt Market That Drives Decisions
Start from the decision, not the questionnaire
The strongest studies begin with a clear statement: "This survey will help us decide X." Examples include:
- Whether to launch a new instalment product and at what ticket size.
- Which governorates to prioritise for distribution expansion.
- How to reposition a brand in response to price sensitivity.
- Whether to partner with a specific consumer-finance provider or bank.
- How to communicate data privacy and consent in a trusted way.
Every question in the questionnaire should link back to one or more of these decisions. If a question does not inform a decision, it should be challenged or removed.
Native Arabic design, not translation
A telephone survey in Egypt market must sound natural to respondents. This means:
- Writing questions directly in Egyptian Arabic where appropriate, not just Modern Standard Arabic.
- Avoiding literal translations of English concepts that may not exist locally.
- Testing scripts with a small sample before full fieldwork to identify confusing or uncomfortable items.
- Training interviewers to explain concepts like household income, instalment plans or digital wallets in simple, non-judgmental language.
This is not machine language. It is research communication designed for how Egyptians actually speak and think.
Robust sampling and quality control
Effective sampling designs often combine:
- Geographic stratification by governorate or region.
- Urban and rural quotas aligned with the target population.
- Age, gender and income brackets relevant to the product or service.
- Mobile and landline frames to reduce coverage bias.
- Screening questions to identify relevant users, buyers or decision-makers.
Quality control should include:
- Programmed skips and question logic to avoid irrelevant questions.
- Real-time quota monitoring to ensure balanced samples.
- Call-outcome tracking such as answered, busy, no answer, refused and call-back.
- Supervisor dashboards to spot issues early, such as unusually short interviews or high refusal rates.
- Audio recording and quality checks for selected calls.
These practices ensure that results are reliable enough to base strategic decisions on.
The Bottom Line for International Businesses
If you are an international business looking at Egypt in 2026, three messages stand out:
- Consumers are adapting, not withdrawing. High inflation and price pressure are real, but spending continues, often reshaped through instalments, smaller packs and value-seeking.
- Finance is now part of the product. Consumer finance and BNPL are no longer add-ons; they are central to how many Egyptians access electronics, appliances, vehicles and mobile phones.
- Businesses are cautiously optimistic but still constrained. The PMI is nearing growth territory, hiring is rebounding and new companies are forming, yet weak orders and cost pressures remain.
In this context, a telephone survey in Egypt market gives international teams a clear, current and culturally grounded view of what consumers and businesses are really doing and thinking. It turns macro headlines into actionable insights: where to focus, what to offer, how to price and how to communicate.
Ready to See Egypt Clearly?
If your team is considering a telephone survey in Egypt market, the next step is a focused conversation about your decisions, your target audience and the insights you need.
Contact CATI Africa to discuss your research objectives, sampling requirements and fieldwork timeline. Our team can help you design a study that international stakeholders can trust and act on.